
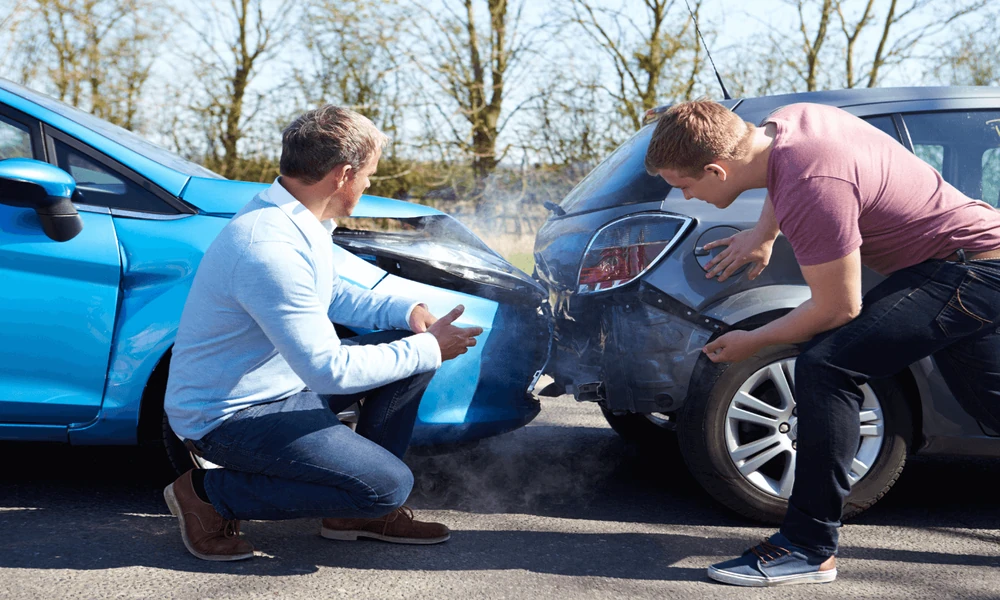
Most people picture a car accident as having a villain and a victim. Real crashes are messier. Someone was a little over the speed limit. Someone else changed lanes without a full look. The road was wet, the light was bad, and everyone was tired. When the claims process starts, you may be surprised to hear the other driver’s insurer suggest that part of the blame belongs to you.
That doesn’t necessarily end your claim, and in Washington it doesn’t come close to it. But it does change the math, and it’s worth understanding before the first phone call from an adjuster.
The rule behind the conversation
Washington follows what lawyers call pure comparative fault. The statute itself is short. Under RCW 4.22.005, any fault chargeable to the person bringing the claim reduces the damages awarded in proportion to that fault, but it does not bar recovery.
Put simply, being partly responsible doesn’t wipe out your claim. It trims it. A person found mostly at fault can still recover something, which is not true in every state. Some states cut off recovery at fifty percent or at any fault at all, so advice you picked up from a friend in another state may not apply here.
Where the percentages come from
Nobody hands down a fault number at the scene. It emerges from evidence: the police report if there is one, photos of the vehicles and the road, witness accounts, traffic camera or dashcam footage, vehicle damage patterns, and sometimes expert analysis of how the crash unfolded. Insurers read that evidence, form their own view, and negotiate. If a case goes to trial, a jury decides.
A quick example makes it concrete. Suppose a jury decides your damages total $100,000, and it finds you twenty percent at fault because you were slightly over the limit when another driver pulled out in front of you. Your recovery drops by twenty percent, to $80,000. The other driver’s share is the rest. The numbers in a real case are never that tidy, but the logic is the same.
Why the percentage becomes a negotiation
Here is the part that catches people off guard. An insurance company has every reason to push your share of fault higher, because every point it assigns to you is a point it doesn’t pay. Adjusters are trained, polite, and very good at asking questions that sound casual. “Were you in a hurry?” “Did you see the car before it pulled out?” Honest answers, given without context, can end up in a file as evidence against you.
If you’ve been hurt and the other side is already pointing back at you, it helps to talk with a Washington injury attorney early. A firm like The Jones Firm can look at how fault is being assigned, check whether the evidence supports it, and handle the insurer so you aren’t answering questions alone while you’re recovering. Whether you hire anyone is your call, but at least understand what’s at stake in those early conversations.
Small things that quietly raise your share
Some of the most damaging moments in a claim have nothing to do with the crash itself.
Apologizing at the scene is a common one. “I’m so sorry” is a reflex, often just politeness, but it can be repeated later as an admission. Gaps in medical treatment are another, because a long pause can be read as proof that you weren’t really hurt. Social media posts are a third. A photo from a weekend hike, taken while you’re claiming back pain, gets noticed. And giving a recorded statement to the other driver’s insurer before you’ve sorted out what happened can lock in details you later realize were wrong.
None of this means you should be secretive or uncooperative. It means being careful, accurate, and aware that the other side is building a file.
Fault isn’t always just two drivers
Crashes frequently involve more than two parties. A road with a defect, a poorly maintained vehicle, a rideshare company, or an employer whose driver was on the job can all enter the picture, and Washington’s rules look at the fault of everyone who contributed. Claims against government entities, such as a city that failed to fix a dangerous intersection, follow their own procedures and notice requirements, which differ from ordinary claims. If a road or signal might have played a part, mention that early instead of assuming it can’t matter.
The clock keeps running
There’s also a deadline. In Washington, most personal injury claims must be filed in court within three years under RCW 4.16.080, and different rules apply to certain claims, such as those against public agencies or involving medical care. Three years sounds generous, but evidence fades, witnesses move, and insurers don’t wait. Treat the deadline as an outer edge, not a target.
A last thought
Hearing that you may share some blame for a crash is unsettling, especially when you’re hurting and dealing with bills. Try to remember that in Washington it’s a factor in the calculation, not a verdict on your right to be compensated. Keep records, get medical care, be honest and careful in what you say, and get advice from a qualified attorney if the fault question starts to loom over your claim. Understanding the rule won’t make the situation pleasant, but it will make it less mysterious, and that matters when you’re trying to make decisions on little sleep.
This article is general information, not legal advice, and reading it does not create an attorney client relationship. Laws change and every case is different, so speak with a licensed attorney about your situation.
